Accident at Work Solicitor in Northern Ireland: Your Rights, Compensation and Can You Be Dismissed for Claiming?

Having an accident at work is stressful enough without worrying about your job. If you’ve been injured on the job in Northern Ireland, speaking to an experienced accident at work solicitor can help you understand whether you’re entitled to compensation, and what protection the law gives you at work. Your employer cannot lawfully dismiss you simply because you have exercised a protected employment right or raised legitimate health and safety concerns — but making a personal injury claim is not, in itself, an automatic unfair dismissal ground, so the circumstances surrounding any dismissal are important. This guide explains your rights, what compensation may cover, and exactly what protection the law gives you if you’re worried about losing your job.

This article provides general information about the law in Northern Ireland and is not a substitute for individual legal advice. Every case depends on its own facts.


Do I Have a Right to Claim for an Accident at Work?


Employers in Northern Ireland have a legal duty to take reasonable care for the health and safety of everyone in their workplace. This duty is set out primarily in the Health and Safety at Work (Northern Ireland) Order 1978, alongside a range of more specific regulations covering areas like manual handling, work equipment and personal protective equipment.

If you were injured because your employer failed in this duty — for example, through unsafe conditions, inadequate training, faulty equipment or poor supervision — you may have grounds for a personal injury claim, regardless of whether you’re still working there or have since left.

A claim may be possible where your employer failed to:

  • provide a safe place of work
  • give you proper training or supervision
  • provide suitable, well-maintained equipment
  • carry out adequate risk assessments
  • provide necessary personal protective equipment (PPE)
  • put safe systems of work in place
  • act on known hazards or previous near-misses

An employer is not automatically liable for every accident — but if reasonable safety steps weren’t taken, you may well have a valid claim.


Common Types of Workplace Accidents


Workplace injuries can happen in almost any setting, but some patterns come up again and again:

  • Slips, trips and falls — often caused by wet floors, trailing cables, poor lighting or cluttered walkways
  • Falls from height — particularly common in construction, where missing guardrails or inadequate fall protection are frequent causes
  • Being struck by falling objects — common in warehousing and construction due to poor stacking or storage
  • Manual handling and lifting injuries — back and shoulder injuries from repeated or incorrect lifting
  • Machinery and equipment accidents — including defective or poorly maintained machinery
  • Burns — common in hospitality, manufacturing and processing environments
  • Repetitive strain injury (RSI) — from prolonged repetitive movement without adequate breaks
  • Exposure-related conditions — including noise-induced hearing loss, vibration white finger and occupational dermatitis, which can develop gradually over years

What Should I Do After a Workplace Accident?


Taking the right steps early can make a significant difference to any later claim:

  1. Seek medical attention — for your health first, but this also creates an official record of your injury.
  2. Report the accident to your employer and make sure it is recorded appropriately, ideally in the workplace accident book. Depending on the circumstances and severity of the incident, your employer may also have a legal obligation to report it to the Health and Safety Executive for Northern Ireland (HSENI) under the Reporting of Injuries, Diseases and Dangerous Occurrences Regulations (Northern Ireland) 1997 (RIDDOR). This reporting obligation normally falls on the employer or other “responsible person,” rather than on the injured employee.
  3. Gather evidence where you can — photos of the hazard or accident scene, photos of your injuries, and the names of any witnesses.
  4. Keep records — of time off work, medical appointments, and any financial losses such as travel costs or lost earnings.
  5. Speak to a solicitor before accepting any offer from your employer or their insurer. Early offers are often lower than what you may be entitled to.

What If the Accident Was Partly My Fault?


You can still make a claim even if you bear some responsibility for what happened. Many accidents involve shared responsibility — for example, you may not have used PPE correctly, but your employer may also have failed to provide proper training or supervision.

Where you’re found partly responsible, this is known as contributory negligence, and your compensation is reduced by a percentage that reflects your share of the blame. For example, if a court finds you and your employer equally responsible, you would typically receive 50% of the compensation you’d otherwise be entitled to.

If you were entirely responsible for the accident yourself, with no failure on your employer’s part, a claim is unlikely to succeed.


How Much Compensation Could I Receive?


Compensation in a successful accident at work claim is generally made up of two parts:

  • General damages — compensation for the injury itself: the pain, suffering and any long-term effects on your quality of life.
  • Special damages — compensation for financial losses caused by the injury, which may include:
    • loss of earnings (past and future)
    • medical and treatment costs
    • travel expenses
    • care and assistance costs
    • rehabilitation costs

The amount depends heavily on the severity of the injury, your recovery time, and the long-term impact on your ability to work and live as before. A solicitor can give you a realistic estimate once medical evidence is available — be cautious of any calculator or estimate that doesn’t account for your specific circumstances.


Time Limits for Making a Claim


Under Article 7 of the Limitation (Northern Ireland) Order 1989, the standard time limit for a personal injury claim, including an accident at work claim, is three years from the date the cause of action accrued, or, if later, your “date of knowledge” — broadly, the date you first knew your injury was significant and linked to your employer (relevant for conditions that develop gradually, like RSI or hearing loss).

There are some important exceptions:

  • Under 18s — the three-year clock doesn’t start until your 18th birthday, giving you until you turn 21.
  • Lack of mental capacity — there may be no time limit while the person concerned lacks capacity to bring a claim themselves.
  • Fatal accidents — different limitation provisions apply depending on the nature of the claim and who is bringing it. Claims under the Fatal Accidents (Northern Ireland) Order 1977 are generally subject to a three-year limitation period, with the precise starting point depending on the circumstances and, in some cases, the claimant’s date of knowledge.

There is also a statutory discretion under Article 50 of the Limitation (Northern Ireland) Order 1989, which can, in appropriate circumstances, allow a late personal injury or fatal accident claim to proceed. This is discretionary, however, and should never be relied upon as an alternative to complying with the normal limitation period.

It’s best to seek advice as early as possible. The longer you wait, the harder it can become to gather evidence and trace witnesses.


Can My Employer Fire Me for Making a Claim?


This is one of the most common concerns people have after an accident at work. Many employees worry that making a compensation claim will damage their relationship with their employer or even put their job at risk.

Your employer cannot lawfully dismiss you simply because you have exercised a legal right or because you have raised legitimate health and safety concerns. However, it is important to distinguish between making a personal injury claim and the specific health and safety activities and concerns that are protected by employment legislation — the two are not automatically the same thing in law.

Your legal protection

Employment rights in Northern Ireland are principally governed by the Employment Rights (Northern Ireland) Order 1996.

If an employer dismisses an employee because of a protected health and safety reason, the dismissal may be automatically unfair, meaning the usual qualifying period for an ordinary unfair dismissal claim does not apply. The precise protection depends on what the employee actually did and the reason for the employer’s decision.

Ordinary unfair dismissal

For an ordinary unfair dismissal claim in Northern Ireland, an employee will generally need at least one year’s continuous service — this differs from Great Britain, where the qualifying period is longer.

If an employer dismisses an employee because they have made a genuine complaint about health and safety, or for another reason protected by the legislation, different rules may apply and the one-year qualifying period may not be required.

Automatic unfair dismissal on health and safety grounds

Article 132 of the Employment Rights (Northern Ireland) Order 1996 provides specific protection in health and safety cases.

For example, a dismissal may be automatically unfair where the reason, or principal reason, is connected with certain health and safety activities — such as carrying out designated health and safety duties, raising certain safety concerns through proper channels, or leaving, or refusing to return to, a workplace in circumstances of danger which the employee reasonably believed to be serious and imminent and could not reasonably have been expected to avert.

This protection is particularly important where an employee has raised genuine concerns about unsafe working conditions. It is important to remember, however, that making a personal injury compensation claim is not, by itself, necessarily an automatically unfair reason for dismissal — the circumstances surrounding the dismissal need to be examined carefully.

Constructive dismissal

An employer does not necessarily have to dismiss you expressly for there to be an employment claim.

If an employer seriously breaches the terms of your employment and, as a result, you feel you have no realistic option but to resign, you may potentially have a claim for constructive dismissal.

This is a fact-sensitive area. A general deterioration in the employment relationship following an accident or compensation claim will not automatically amount to constructive dismissal, but significant changes in treatment, disciplinary action or working conditions may be relevant.

Detriment short of dismissal

Employees and certain workers also have statutory protection against suffering a detriment in particular health and safety circumstances. Article 68 of the Employment Rights (Northern Ireland) Order 1996 provides protection where a worker is subjected to a detriment because of certain actions taken in response to circumstances of serious and imminent danger, or because they have taken appropriate steps to protect themselves or others. Since 2021, this protection has also been extended to certain “limb (b)” workers, not just employees.

Anyone who has experienced adverse treatment after an accident or claim should keep a written record of what happened, including dates, communications, changes to working arrangements and the names of any witnesses. However, there is no blanket rule that every negative action taken by an employer following a personal injury claim will amount to an unlawful detriment — the legal basis for any complaint depends on the particular facts.

What if I am dismissed after making a claim?

If you believe you have been dismissed because you raised health and safety concerns, or for another automatically unfair reason, you should get employment-law advice promptly.

An employment claim is separate from your personal injury claim. You may potentially have both a claim for compensation arising from the accident and a separate employment claim arising from the way your employer treated you afterwards.

Time limits for an employment claim

Employment claims have much shorter time limits than personal injury claims. A claim to an Industrial Tribunal in Northern Ireland will normally need to be presented within three months of the relevant act or dismissal, subject to the statutory rules on early conciliation and any applicable extension. You should contact the Labour Relations Agency (LRA) as soon as possible if you believe you have been unfairly dismissed or subjected to an unlawful detriment.

Do not assume that the three-year limitation period for a personal injury claim gives you three years to bring an employment claim too — the two are entirely separate, and the employment time limit is far shorter.

How claims are usually handled

In practice, accident at work compensation claims are almost always dealt with by the employer’s insurer, not the employer directly — so your employer isn’t left personally out of pocket, which is often an underlying (if unspoken) worry behind poor treatment following a claim. Most employers handle this professionally, but the legal protections above exist precisely for the cases where they don’t.


What About “No Win, No Fee”?


It’s worth knowing that Northern Ireland’s rules around funding personal injury claims differ materially from the rest of the UK. Conditional fee agreements (“no win, no fee”) are not permitted in Northern Ireland — unlike in England and Wales, where they are a standard, statutory arrangement. Your solicitor should explain clearly, before you proceed, exactly how costs and funding will work for your specific case — ask about this at your first consultation so there are no surprises later.


Frequently Asked Questions


Will I lose my job if I make a compensation claim? Your employer cannot lawfully dismiss you simply because you have exercised a protected employment right or raised legitimate health and safety concerns, and doing so may amount to automatic unfair dismissal in the right circumstances. Making a personal injury claim by itself isn’t automatically a protected reason, though, so if you’re dismissed or treated badly after claiming, it’s worth getting employment-law advice on the specific circumstances promptly.

Can I claim if I still work for the same employer? Yes. Many people successfully claim compensation while remaining in their job. Claims are usually handled by the employer’s insurer rather than the employer personally.

Can I claim against a former employer? Yes, provided you’re within the relevant time limit — generally three years from the accident, or from when you became aware your injury was linked to your work.

What if I’m self-employed? Being self-employed doesn’t automatically rule out a claim. You may still have grounds if you were injured on someone else’s premises, or due to faulty equipment provided by another business.

What if my employer offers me compensation directly? Take advice before accepting anything. An early offer, usually from the employer’s insurer, may be significantly lower than what you’d be entitled to once the full extent of your injury and losses are known.

How long do accident at work claims take? Straightforward claims can settle within months; more complex or seriously disputed cases can take longer, particularly if the full long-term impact of an injury isn’t yet clear. It’s important not to settle too early.


Why Speak to an Accident at Work Solicitor?


If you’ve been injured at work in Northern Ireland, or you’re worried about how making a claim might affect your job, it’s worth speaking to an accident at work solicitor early. A solicitor experienced in this area can advise on the strength of your claim, protect you if your employer reacts unfairly, and make sure you don’t miss any relevant time limits — for either the injury claim or a separate employment claim, if one becomes necessary.


Speak to an Accident at Work Solicitor at Lacey Solicitors


At Lacey Solicitors, our personal injury team acts as accident at work solicitors for clients across Belfast and Northern Ireland, offering clear, straightforward advice on workplace injury claims from the very first call. If you’re unsure whether you have a claim, or concerned about how it might affect your job, get in touch for a free, no-obligation consultation.
Gym Equipment Failure Claim: How a £6,000 Offer Became £14,000


A gym member was injured when a cable machine snapped during normal use.

Liability was denied — but after challenging the gym’s inspection system, the claim settled for £14,000 (up from £6,000).


The Incident


Our client was using a cable crossover machine at his local gym in Belfast when the cable suddenly snapped.

The failure was immediate and unexpected. He lost balance and fell as a result.

What appeared at first to be a routine gym session quickly became a personal injury claim arising from equipment failure during normal use.


Immediate Impact After the Gym Accident


Following the incident:

  • Our client sustained multiple physical injuries
  • He experienced ongoing pain and discomfort
  • He reported anxiety associated with returning to the gym

Although not a high-speed or dramatic accident, the consequences were real and significant.


Why A Gym Accident Claim Was Brought


Gym owners and operators owe a duty to ensure that:

  • Equipment is properly maintained
  • Inspection systems are effective
  • Defective equipment is identified and removed

Where equipment fails during normal use, this often raises a clear question:

Was there a proper and effective system of inspection in place?


Liability Denied


The gym operator’s insurer denied liability at an early stage.

They relied on documentation which they said demonstrated:

  • A system of inspection
  • Regular maintenance procedures

On that basis, they argued the incident was simply an unavoidable accident and invited the claim to be withdrawn.


Challenging the Inspection System in the Gym


The existence of an inspection system is not enough.

The key issue is whether that system is capable of identifying risk before failure occurs.

We sought further disclosure, including:

  • Inspection records
  • Maintenance logs
  • Details of how checks were carried out

Particular focus was placed on the nature of the equipment.

Where a machine involves load-bearing components such as cables, inspections must be sufficiently robust to identify wear and prevent failure.

A cursory inspection is not a safe system.

Following these enquiries, the insurer indicated a willingness to engage on a without prejudice basis.


Evidence Required in Gym Equipment Failure Cases


Whether bringing or defending a case, the evidence is usually the same.

In equipment failure claims, the outcome often turns on documentation. Standard evidence typically includes inspection and maintenance records, manufacturer servicing guidance, incident reports, and photographs of the defective equipment.

A system that exists on paper will not assist a defendant if it is not effective in practice — the critical question is whether it was capable of identifying risk before the failure occurred.


The First Offer from the Insurance Company


The insurer made an initial offer of £6,000.00

We did not consider this to properly reflect:

  • The nature of the injuries
  • The combined impact of those injuries
  • The overall effect on the client

We therefore rejected the offer.


How Much is the Claim Worth and Legal Framework


The claim was assessed by our office with by reference using the principles outlined in our previous articles:

The key principle from Wilson v Gilroy is that:

Where multiple injuries arise, the court must assess both individual injuries and the overall global impact.

Applying this approach, we demonstrated that the insurer’s valuation was insufficient.


Why the Case Settled


This case ultimately turned on two key issues:

1. The inspection system

Was it genuinely capable of identifying and preventing risk?

2. The valuation of injuries

Had the insurer properly assessed the claim on a global basis?

The combination of these factors resulted in a significantly improved settlement.


Final Outcome


The claim settled for £14,000, more than double the insurer’s original offer.


What This Case Shows


  • An inspection system must be effective, not merely documented
  • Equipment failure can give rise to a valid personal injury claim
  • Early insurer offers may undervalue claims
  • Proper legal analysis can significantly improve outcomes

Frequently Asked Questions

Who is responsible if gym equipment breaks?

The gym operator is responsible for ensuring equipment is safe. If failure occurs due to poor maintenance or inspection, they may be liable.


Can you bring a gym accident claim in Northern Ireland?

Yes. Where a gym fails to take reasonable steps to maintain equipment, an injured person may bring a claim.


What if the gym says the accident was unavoidable?

This is a common defence. The key issue is whether there was a system capable of identifying risk before the failure occurred.


How are gym injury claims valued?

Claims are assessed using the Green Book, relevant case law, and the overall impact of the injuries sustained.


Injured in a Gym Accident?


If you have been injured due to faulty gym equipment or poor maintenance, you may have a claim.

At Lacey Solicitors, we are recognised experts in public liability and insurance litigation, regularly acting for major insurers as well as individual clients.

This dual perspective provides a distinct advantage. We understand how insurers:

  • assess liability

  • evaluate evidence

  • approach settlement negotiations

That insight allows us to anticipate arguments, challenge positions effectively, and maximise outcomes for our clients.

Whether acting in defence of complex claims or pursuing compensation on behalf of injured individuals, our approach is the same — detailed, strategic, and evidence-led.

Contact us using our online portal to discuss you case.


Farm Accident Claims in Northern Ireland: Injuries, Risks and Your Legal Rights


Farming Accidents in Northern Ireland


Farming is one of the most important industries in Northern Ireland, supporting rural communities and providing employment to thousands of people.

However, agriculture is also one of the most dangerous occupations in the region.

Every year farmers, agricultural workers, contractors and family members are injured in accidents involving livestock, machinery, falls from height and hazardous gases.

These incidents can cause life-changing injuries, long-term disability and significant financial hardship for farming families.

While some accidents are unavoidable, many occur because basic safety procedures were not followed or proper systems were not in place.

Where negligence is involved, injured individuals may be entitled to pursue a farm accident compensation claim.


Farming Safety Statistics in Northern Ireland


Farming consistently records a disproportionate number of workplace fatalities.

According to data from the Health and Safety Executive for Northern Ireland (HSENI) and the Farm Safety Partnership, agriculture continues to account for a significant proportion of work-related deaths.

Recent surveys show that:

  • 1 in 10 farmers report a minor injury or near miss each year
  • 2% of farmers report accidents requiring medical attention
  • Nearly half of those injured suffer fractures
  • 27% require more than 30 days off work

Northern Ireland has approximately 48,000 people working across almost 25,000 farms, yet agriculture accounts for a large share of serious workplace incidents.

This highlights the importance of improving safety standards across the sector.


The “Stop and Think SAFE” Farm Safety Campaign


To tackle the high number of agricultural accidents, the Farm Safety Partnership launched the fantastic “Stop and Think SAFE” campaign.

The SAFE message focuses on the four most common causes of serious farm accidents:

  • Slurry
  • Animals
  • Falls
  • Equipment

Understanding these risks is essential to preventing injuries on farms. Lacey Solicitors advises that these four areas provide a sensible starting point for any farmer or agricultural employer when carrying out appropriate health and safety checks and reviewing working practices on the farm.


Slurry Accidents and Toxic Gas Exposure


Slurry tanks are a routine part of modern farming but they also present one of the most serious hazards.

Slurry produces a mixture of gases including:

  • methane
  • carbon dioxide
  • ammonia
  • hydrogen sulphide

Hydrogen sulphide is particularly dangerous because it can be rapidly fatal to both humans and animals.

The highest risk occurs during slurry mixing, when gases are released into the surrounding air.

Safety guidance recommends:

  • removing animals from sheds before mixing
  • opening all doors and ventilation points
  • keeping children away from the area
  • mixing slurry on windy days where possible

Unfortunately, slurry incidents often involve multiple casualties, as people instinctively attempt to rescue others who have collapsed as seen in 2012 in NI when a tragic accident took the lives of three members of the same family.  They were overcome with toxic fumes when trying to rescue one another.


Livestock Accidents on Farms


Working with animals will always involve some level of risk.

However, incidents involving livestock remain the most common cause of farm injuries.

According to farm safety and national reports both in Northern Ireland and the Republic of Ireland, livestock incidents account for approximately one third of reported farm accidents.

High-risk situations include:

  • handling bulls
  • dealing with freshly calved cows
  • moving cattle through poorly designed handling systems
  • working with animals that are unfamiliar with handlers

Even experienced farmers can suffer serious injuries when animals become frightened or agitated.

Good livestock handling facilities and proper planning are essential to reducing these risks.


Falls from Height on Farms


Falls are another leading cause of serious agricultural injuries and we have highlighted the issue in a previous article.

These accidents frequently occur during routine maintenance tasks such as:

  • repairing barn roofs
  • stacking bales
  • cleaning gutters
  • accessing loft spaces

Farm buildings often contain fragile roofing materials which can collapse without warning.

Working at height should always be carefully planned and appropriate equipment should be used.


Machinery and Farm Equipment Accidents


Modern agricultural machinery allows farms to operate efficiently and productively.

However, machinery is also involved in more than one third of fatal farm accidents.

Common causes of machinery accidents include:

  • missing guards on power take-off (PTO) shafts
  • poorly maintained tractors
  • lack of visibility around vehicles
  • attempting to repair machinery while it is still powered

These incidents can result in devastating injuries including:

  • amputations
  • crush injuries
  • spinal injuries
  • severe lacerations

Machinery accidents often require extensive medical treatment and rehabilitation.


Farm Safety and Children


Children living on farms are particularly vulnerable.

Because of their age and lack of experience, they may not fully understand the risks posed by animals, machinery and slurry tanks.

Safety guidance recommends that farms should have segregated play areas where children can play safely away from working machinery.

Sadly, many agricultural tragedies involve young family members who were simply playing near farmyards.


Common Injuries in Farm Accidents


Farm accidents frequently result in serious injuries because of the size of machinery and the unpredictable behaviour of animals.

Common injuries include:

  • broken bones and fractures
  • crush injuries
  • amputations
  • head and brain injuries
  • spinal injuries
  • severe lacerations

These injuries can prevent farmers or agricultural workers from returning to physical work.

For many farming families, the loss of one person’s labour can have a major financial impact on the farm business.


Can I Bring a Farm Accident Claim?


Many people assume that only farm employees can bring a legal claim following an accident.

In reality, a variety of people may be entitled to pursue compensation.

This may include:

  • farm employees
  • self-employed agricultural workers
  • contractors
  • visiting vets or professionals
  • delivery drivers
  • family members living on the farm

Each case will depend on the circumstances of the accident and who was responsible for maintaining safe conditions on the farm.


What Should You Do After a Farm Accident?


If you are injured in a farming accident, taking the right steps early can be important.

You should:

• seek medical attention immediately
• report the accident to the farm owner or employer
• record the details of the incident
• take photographs of the location or equipment involved
• obtain contact details for witnesses

Farm accident claims often involve complex investigations including machinery inspections, expert reports and witness evidence.

Early legal advice can help ensure that important evidence is preserved.


Farm Accident Compensation in Northern Ireland


If negligence can be established, an injured person may be entitled to claim compensation.

Compensation may include damages for:

  • pain and suffering
  • loss of earnings
  • medical treatment
  • rehabilitation costs
  • care needs
  • future financial losses

Serious injuries may have long-term consequences, particularly where they affect a person’s ability to work in agriculture.


Frequently Asked Questions About Farm Accident Claims


How long do I have to bring a farm accident claim?

In most cases, personal injury claims in Northern Ireland must be brought within three years of the accident.

Exceptions may apply where the injured person is a child or lacks capacity.


Can I claim if I was injured by livestock?

Yes.

Claims may arise where livestock injuries occur because of:

  • unsafe handling facilities
  • inadequate fencing or gates
  • failure to properly control animals
  • unsafe working practices

Can I claim if I am self-employed?

Yes.

Self-employed agricultural workers may still be entitled to compensation if the accident occurred because of unsafe working conditions on the farm.


What if the accident happened on a family farm?

Many people worry about bringing a claim against a family member.

In practice, claims are usually dealt with by farm insurance policies, meaning insurers handle the claim.


Farm Accident Solicitors in Northern Ireland


Investigating farm accidents often requires specialist knowledge of:

  • agricultural machinery
  • livestock handling practices
  • workplace safety regulations
  • HSENI guidance

Because these cases can involve complex circumstances, it is important to seek advice from solicitors experienced in serious personal injury claims.


Conclusion


Farming will always involve risk, but many serious accidents are preventable.

Campaigns such as Stop and Think SAFE and online learning tools such as www.farmsafenet.org highlight the importance of safety when working with slurry, animals, heights and machinery.

When accidents do occur, they can have devastating consequences for farming families and rural communities.

Understanding the risks and the legal rights of those injured is an important step in improving safety across Northern Ireland’s agricultural sector.

High Court Dismisses Workplace Trip Claim: Not Every Accident Creates Liability

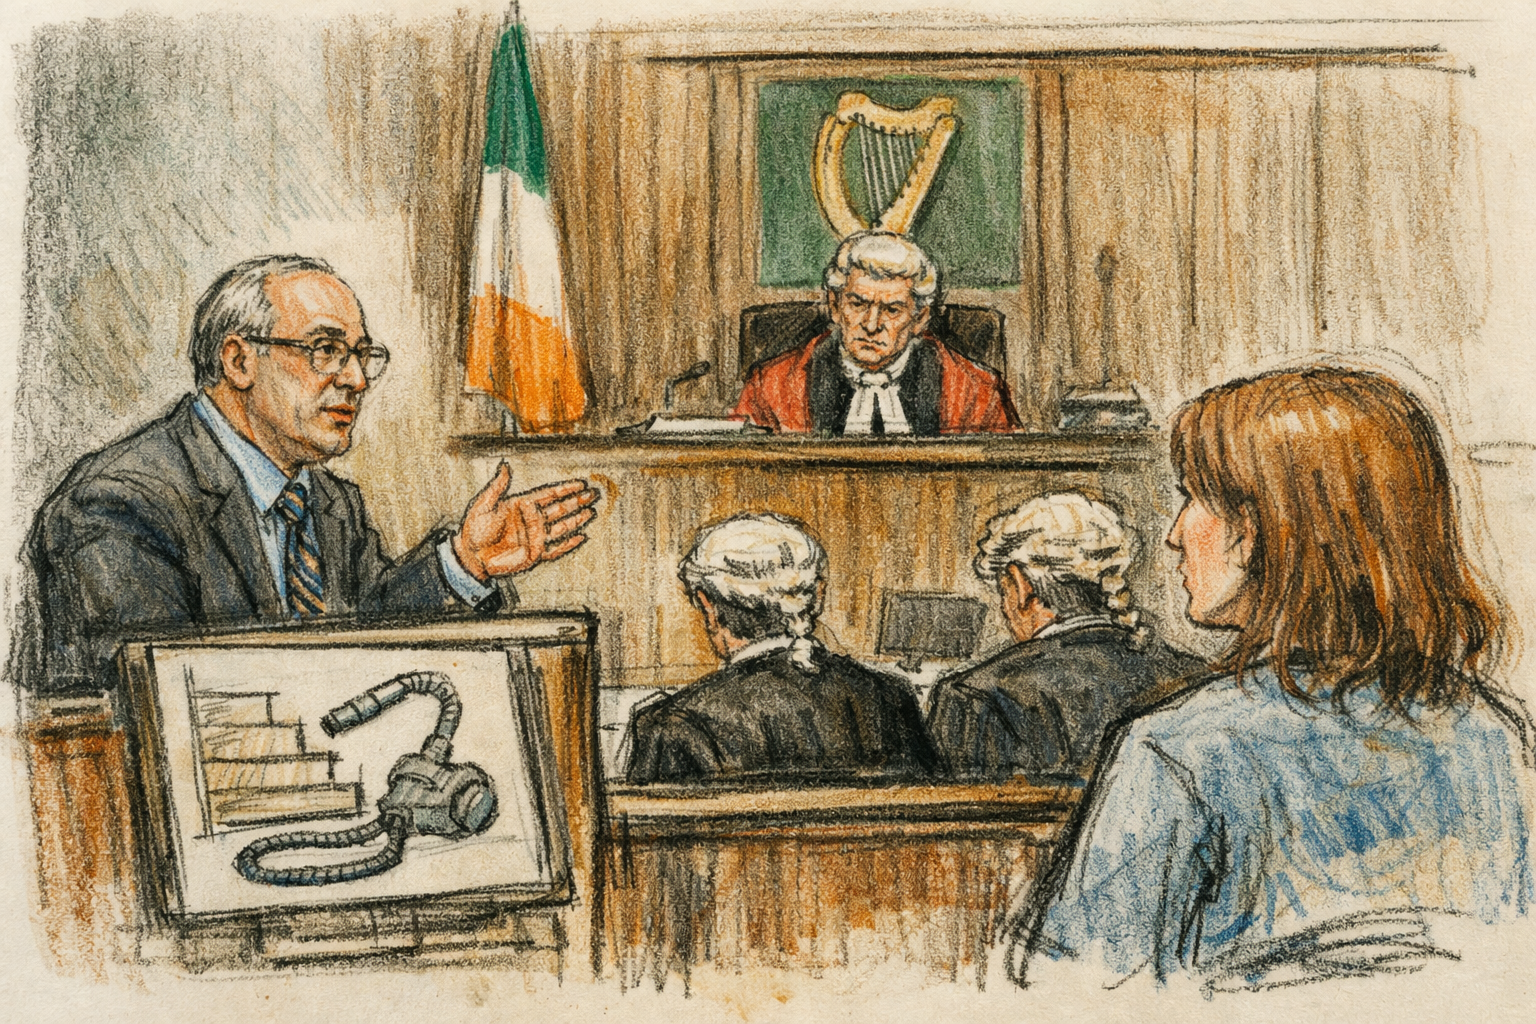
A recent High Court decision will be of considerable interest to insurers and injury practitioners dealing with employer liability claims in Ireland. In Sharon Walsh v Juniper Orthodontics Limited, the High Court dismissed a personal injuries action brought by a dental assistant who alleged she was injured after tripping on the hose of a vacuum cleaner while cleaning stairs at her workplace.

Delivering judgment, Mr Justice Anthony Barr emphasised an important principle that frequently arises in workplace accident litigation: the law requires employers to act reasonably, not perfectly. As the Court made clear, employers are not required to eliminate every conceivable risk that might arise during ordinary workplace activities.

The decision provides useful guidance for insurers defending employer liability claims and illustrates how courts continue to distinguish between an unfortunate accident and actionable negligence.


Background to the Claim


The plaintiff, aged 54, had worked as a dental assistant in a small orthodontic practice since 2007.

The accident occurred on 20 June 2016 at approximately 3pm while the plaintiff was vacuum cleaning a flight of stairs during a gap in the clinic’s patient schedule. As was common practice during quieter periods, staff members would carry out light cleaning duties when no patients were being treated.

According to the plaintiff, she switched off the vacuum cleaner and left it at the bottom of the stairs with the rigid arm resting against the banister. She then went upstairs to check whether the receptionist was on the telephone, as the noise of the vacuum cleaner could interfere with phone conversations.

While she was waiting upstairs, she alleged that the rigid arm of the vacuum cleaner fell over, causing the flexible hose to lie across one of the steps. When she returned and descended the stairs, she stepped onto the hose, lost her balance and sustained an inversion injury to her right ankle.

Medical investigations later revealed that the plaintiff had suffered an avulsion fracture of the distal fibula together with ligament damage to the ankle.


Delay in Notification


One feature of the case which will be familiar to insurers was the significant delay in notification of the claim.

Although the alleged accident occurred in June 2016, the employer gave evidence that he did not receive notification of the circumstances of the incident until a solicitor’s letter issued almost two years later in April 2018. By that stage, the clinic’s internal CCTV system had already overwritten any recordings from the relevant period.

This accident occured in 2016, almost two years prior to the amendment of section 8 of the Civil Liability and Courts Act 2004, which now requires a plaintiff in a personal injuries action to serve a letter of claim within one month of the cause of action.

The provision obliges the court to consider drawing appropriate inferences and, where the interests of justice so require, making costs consequences where this requirement is not complied with. For defendants and insurers, the legislative framework underscores the importance of prompt notification so that incidents can be investigated while contemporaneous evidence remains available.


Alleged Unsafe System of Work


The plaintiff alleged that the employer had failed to provide a safe system of work.

Engineering evidence was called on her behalf suggesting that the cleaning process was unsafe because the person vacuuming the stairs had to stop the hoover periodically and check whether the receptionist was on the telephone.

The plaintiff’s expert suggested a number of alternative safety measures, including:

  • Carrying out cleaning outside working hours
  • Installing a warning light system connected to the reception desk
  • Soundproofing the reception area

However, the court ultimately rejected the suggestion that these measures were necessary or required under the law.


The Court’s Findings


The High Court concluded that the incident was simply an unfortunate accident rather than the result of negligence.

Mr Justice Barr stated:

“That was a very unfortunate accident. But that is all it was. It was an accident.”

The court observed that interruptions while vacuum cleaning stairs are entirely ordinary. People frequently stop such tasks to answer a phone, attend to someone upstairs or deal with another task.

The judge stated:

“Every day up and down the country, when people are carrying out vacuum cleaning operations on a flight of stairs… the person doing the vacuum cleaning may have to stop for any number of reasons.”

Importantly, the court accepted that the vacuum cleaner arm falling over was simply something that can occur without negligence on anyone’s part.

As Mr Justice Barr explained:

“From time to time when the rigid arm of a hoover is left propped in an upright position, it will sometimes topple over and come to rest on the ground. That is not anybody’s fault, it just happens from time to time.”


Reasonableness – Not Risk Elimination


As always, hindsight is 20/20, but in this case, the court was quick to reject evidence advanced by the Plaintiff’s engineer of steps that should have been taken to eliminate risk.

Addressing the suggestions made by the plaintiff’s expert engineer, the court stated:

“It is always possible to come up with steps that can be taken to eradicate any possible accident. However, that is not the duty that is placed on an employer… An employer is only required to take reasonable steps to prevent an accident that is reasonably foreseeable.”

This statement provides a clear reminder that the legal standard is reasonableness, not the elimination of every conceivable hazard.


Conclusion


For insurers and defence practitioners, the decision reinforces several familiar but important principles:

Not every workplace accident creates liability
The courts recognise that accidents can occur even where a workplace is reasonably operated.

Reasonable systems of work remain the legal standard
Employers are required to take reasonable precautions, not eliminate all possible risks.

Expert hindsight will not necessarily establish negligence
Courts remain cautious about retrospective suggestions that theoretically safer systems could have been implemented.

Early notification of incidents remains critical
Delays in notification may result in the loss of important evidence, including CCTV or witness recollection.

The High Court’s decision in Sharon Walsh v Juniper Orthodontics Limited serves as a useful reminder that not every workplace accident will give rise to legal liability.

Where an employer has implemented a reasonable system of work and the incident arises from an ordinary everyday activity, the courts will not impose liability simply because an injury occurred.

The phrase “where there is blame, there is a claim” is an oft repeated mantra in personal injury litigation. This judgment however is a reminder that while accidents may happen, liability does not follow the same – negligence must still be proven to sustain the claim.

Interim Payments in Serious Injury Claims: What the NI High Court Said in Stewart v Northern Health and Social Care Trust [2026]

In a previous article on the Lacey Solicitors website we discussed how interim payments in personal injury claims in Northern Ireland can provide vital financial support to injured victims while litigation progresses through the courts.

Interim payments are particularly important in catastrophic injury and medical negligence claims, where the injured party may require urgent funding for accommodation, rehabilitation, treatment or care long before the case reaches trial.

A recent decision of the High Court of Justice in Northern Ireland — Sarah Stewart v Northern Health and Social Care Trust [2026] NIKB 2 — provides a useful and detailed illustration of how the courts approach applications for large interim payments and the caution that judges may exercise when the likely value of a claim remains uncertain.


Background to the Case


The case arose from a claim for damages following an alleged failure to diagnose cauda equina syndrome, a serious spinal condition requiring urgent surgical intervention.

The plaintiff presented to hospital in January 2018 with a number of concerning symptoms including:

  • numbness below the level of the umbilicus
  • back pain
  • heaviness in the legs
  • altered sensation
  • urinary and bowel symptoms

Despite these symptoms, she was discharged following her attendance at hospital. Two days later she attended the Royal Victoria Hospital where an MRI scan revealed a large ruptured disc compressing the spinal cord, and emergency surgery was carried out.

The plaintiff subsequently issued proceedings alleging that the delay in diagnosis and treatment had caused significant long-term neurological injury.

The defendant Trust admitted a breach of duty in failing to diagnose the condition when the plaintiff first attended hospital, although causation and the extent of the resulting damage remained disputed.


The Application for an Interim Payment


During the course of the proceedings the plaintiff applied for an interim payment of £500,000 pursuant to Order 29 of the Rules of the Court of Judicature (Northern Ireland).

The Trust had previously offered an interim payment of £50,000, but the plaintiff argued that a substantially larger payment was justified given the seriousness of her injuries and the likely value of the claim.

The Master initially granted the application and ordered the Trust to make the payment.

The Trust subsequently appealed that decision to the High Court.


The Legal Framework for Interim Payments


The High Court reviewed the provisions contained in Order 29 of the Rules of the Court of Judicature (Northern Ireland).

In personal injury actions the court may order an interim payment where it is satisfied that:

  • the defendant has admitted liability;
  • judgment has been obtained with damages to be assessed; or
  • if the action proceeded to trial, the plaintiff would obtain judgment for substantial damages.

If those conditions are satisfied, the court has a discretion to order a payment not exceeding a reasonable proportion of the damages likely to be recovered at trial.

Importantly, the court must effectively place itself in the position of the trial judge and ask whether, on the evidence currently available, the plaintiff is likely to succeed and obtain a substantial award.


Expert Evidence in the Case


In the Stewart case, the court had the benefit of a joint minute between two medical experts addressing the issue of causation.

Those experts agreed that if the plaintiff had undergone MRI scanning and surgery on the earlier date when she first presented at hospital, she would likely have experienced a significantly better outcome.

Among the consequences identified were:

  • worsening lower limb weakness
  • persistent sensory disturbance
  • dysaesthetic pain
  • bladder dysfunction
  • bowel difficulties

The plaintiff also claimed substantial future financial losses, including loss of earnings and accommodation needs.

A forensic accountant retained by the plaintiff estimated the total potential claim to be between £2.46 million and £3.29 million, depending on various assumptions regarding disability and care requirements.


Why did the Court Refuse the Interim Payment?


Although the judge accepted that the plaintiff would recover damages if the case proceeded to trial, the court ultimately refused the application for an interim payment of £500,000.

The key difficulty was that too many uncertainties remained regarding the likely value of the claim.

In particular:

  • the defendant had not yet produced its own forensic accountancy evidence
  • expert evidence on several aspects of the claim had not yet been tested
  • the eventual calculation of special damages could vary significantly depending on the outcome of expert meetings and further reports

The judge noted that attempting to estimate the final value of the claim in these circumstances would be “a foolish exercise”.

While it was possible that the final award might exceed £500,000, the court was not satisfied that the figure represented a reasonable proportion of the likely damages, which is the legal test required by Order 29.

Because the application before the court sought only the specific figure of £500,000, the judge had to either grant or refuse that application.

The appeal was therefore allowed and the interim payment application dismissed.


Clarification on the Role of “Need”


An interesting aspect of the judgment concerned the argument that interim payments should be linked to the immediate needs of the plaintiff, particularly in relation to accommodation.  This was an approach taken in Eeles v Cobham Hire Services Ltd [2009] EWCA Civ 204 where the Court of Appeal in England set out a new two stage test for interim judges to consider when making a decision on applications for interim payments.

The High Court in Belfast rejected that approach.

The judge observed that Order 29 does not require the court to consider an individual’s financial need when determining whether to order an interim payment.

Instead, the focus must remain on the statutory test – namely whether the proposed payment represents a reasonable proportion of the damages likely to be recovered.

The court distinguished earlier authorities such as Eeles v Cobham Hire Services Ltd, noting that those decisions largely concerned cases involving periodical payment orders which differ to interim payments.


Practical Lessons for Personal Injury Solicitors


The decision provides several useful insights for practitioners involved in serious injury litigation in Northern Ireland.

Courts adopt a cautious approach

Judges are likely to take a conservative approach when assessing the likely value of a claim at an early stage in proceedings.

Evidence is crucial

Large interim payments are more likely to succeed where:

  • expert evidence is fully developed
  • accountancy evidence has been exchanged
  • the likely value of the claim can be assessed with greater confidence.

The amount sought must be justified

Where an application seeks a specific figure, the court must be satisfied that it represents a reasonable proportion of the likely final award.

If that cannot be demonstrated, the application may fail entirely.


Interim Payments in Catastrophic Personal Injury Litigation

Interim payments remain an important feature of serious injury and medical negligence litigation in Northern Ireland.

Where liability is admitted or where an individual is likely to succeed at trial, the courts have the power to order payments that allow injured individuals to access treatment, accommodation and rehabilitation while their case proceeds.

However, the decision in Stewart v Northern Health and Social Care Trust demonstrates that the courts will exercise that power carefully, particularly where the overall value of the claim remains uncertain.

Pre-existing Injuries and Personal Injury Law: Understanding the “Eggshell Skull” Rule

At Lacey Solicitors, we frequently encounter cases where a plaintiff’s pre-existing condition or vulnerability complicates the assessment of liability and damages. For insurance claims handlers and legal professionals, a solid understanding of the “eggshell skull” principle is essential when evaluating personal injury claims.


What is the “Eggshell Skull” Rule?


The “eggshell skull” rule, sometimes called the “thin skull” rule, is a long-established doctrine in tort law. It requires that a defendant take their victim as they find them. Once a plaintiff establishes that the defendant owed a duty of care and breached that duty causing injury, the defendant is liable for the full extent of the resulting damage — even if the injury is far more severe than could have been anticipated due to a pre-existing condition or unusual vulnerability.

Importantly, while the type of injury must be foreseeable, the extent or severity of the injury need not be. Classic authority for this principle includes Smith v Leech Brain & Co Ltd [1962], where a minor burn triggered cancer due to the plaintiff’s pre-existing condition, and the defendant was held fully liable.


Physical and Psychiatric Injuries


The eggshell skull rule applies not only to physical injuries but also to psychiatric vulnerabilities. In Corr v IBC Vehicles Ltd [2005], an employee developed depression after a workplace injury and later committed suicide. The House of Lords held that the suicide was a development of the depression caused by negligence, rather than a novus actus interveniens, and the employer remained liable.


Josephine Higgins v Coleman & Motor Insurers’ Bureau of Ireland (2025)


The High Court of Ireland recently reaffirmed the eggshell skull principle in Josephine Higgins v Coleman & Motor Insurers’ Bureau of Ireland (2025).

The plaintiff, Ms. Higgins, was holding a parking space on the roadway when a van allegedly struck her left knee, causing a jolt. The defendant disputed the collision and denied liability. The court accepted medical evidence showing that Ms. Higgins suffered serious and ongoing consequences, including a radical personality change. She was diagnosed with a psychiatric adjustment disorder with mixed anxiety and depression, alongside moderate back injuries causing ongoing pain and sciatica.

O’Higgins J applied the eggshell skull principle, holding the defendant liable for the full extent of her injuries, even though they were more severe than might have been expected. The judgment emphasised:

“…due to some weakness or predisposition, a particular injured party suffers much more severe consequences from a relatively innocuous incident than might be expected… the tortfeasor takes his victim as he finds her.”

This reasoning echoes Clarke J’s observation in Walsh v Tipperary County Council [2011] IEHC 503:

“…if personal injury is a foreseeable consequence of whatever wrongdoing is concerned (say the negligent driving of a motor vehicle), then the fact that those injuries may, in the peculiar circumstances of the case, be much more severe than might have been expected, does not deprive the injured party from an entitlement to recover whatever may be appropriate for those injuries.”

Together, Walsh and Higgins confirm that psychiatric vulnerabilities are treated as part of the plaintiff’s condition, do not break the chain of causation, and do not limit recovery. They also demonstrate that the eggshell skull rule operates fully alongside the Personal Injuries Guidelines, ensuring plaintiffs with pre-existing vulnerabilities receive appropriate compensation for serious injuries.


Sykula v O’Reilly [2025] IEHC 638 – Multi-factorial Psychiatric Injuries


While Josephine Higgins involved a straightforward causal link between incident and injury, Sykula v O’Reilly [2025] illustrates how courts address cases where external factors also influence the plaintiff’s psychiatric condition.

In Sykula, the plaintiff suffered anxiety, depression, and PTSD following a road traffic accident. The High Court confirmed that, under the eggshell skull rule, the defendant must take the plaintiff as they find her, meaning pre-existing psychological vulnerability does not absolve the defendant from liability. The “but for” test established that, absent the accident, the plaintiff would not have developed these psychiatric conditions from January 2018 onwards.

However, the court recognised that the plaintiff’s mental health was influenced by numerous external factors not attributable to the accident, including homelessness, social isolation during COVID-19, stressful litigation, and rent arrears that led to emergency hostel accommodation. These factors exacerbated her psychiatric condition over six years. As a result, the court apportioned liability, attributing 50% of her psychiatric injury to the accident, with the remainder arising from other causes.

This demonstrates a key distinction: while the eggshell skull principle ensures liability for pre-existing vulnerabilities, courts will carefully consider multi-factorial influences when assessing damages over time.


Conclusion


The eggshell skull principle remains a cornerstone of personal injury law. It ensures that defendants are fully responsible for the consequences of their negligence, even where a plaintiff’s pre-existing vulnerabilities make the harm unusually severe. At the same time, cases like Sykula show that courts will carefully consider other contributing factors when assessing damages. Together, these cases highlight the balance courts strike between holding defendants accountable and ensuring damages accurately reflect the real-world impact of the injury. For Plaintiffs and defendants alike, the principle serves as a reminder that the law takes the plaintiff as it finds them – and that fairness in compensation must consider both the injury and the individual it affects.

If you would like guidance on a personal injury claim involving pre-existing conditions, or wish to understand how the eggshell skull principle may apply, use our Contact Us section and our team at Lacey Solicitors will be available to provide informed, practical advice.

Lacey Solicitors Property Department – Award-Winning Conveyancing in Northern Ireland

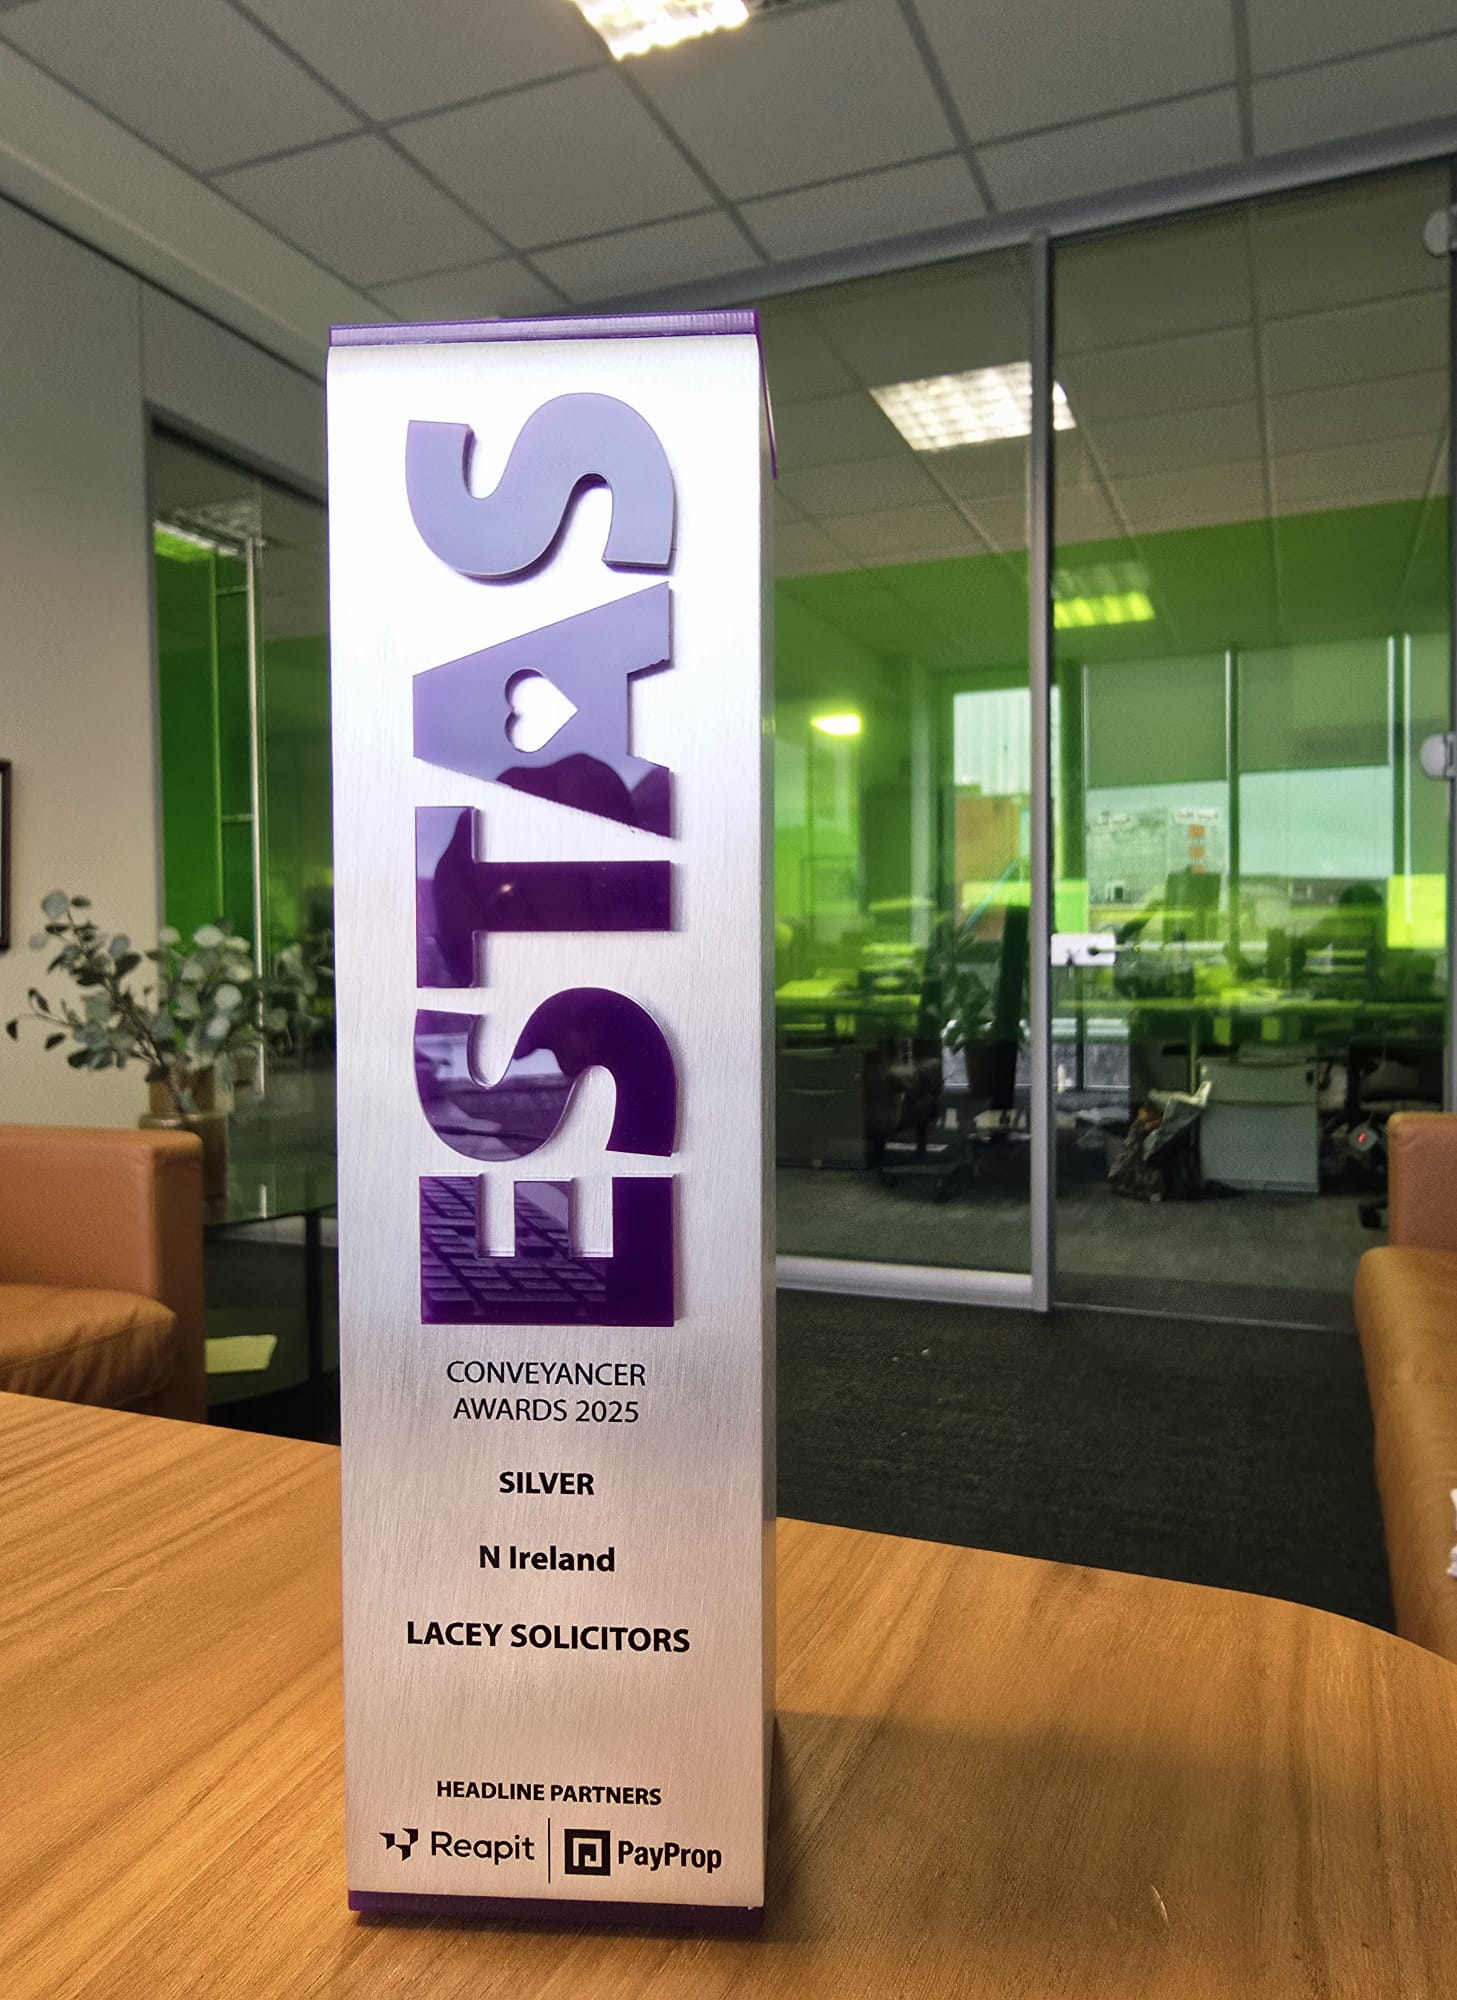
Lacey Solicitors is proud to announce that our Property Department has again been recognised for client care in property law, by achieving Silver at the ESTAs NI Conveyancer Awards 2025.   Lacey Solicitors was also a finalist at the 2025 Irish Law Awards as Property Law Firm of the Year. These accolades reflect our commitment to exceptional service and building trust with clients across Northern Ireland.


Expert Property Solicitors in Northern Ireland


Our Property Department officially opened in 2024, led by William Wilson, a seasoned conveyancing solicitor dedicated to modern, client-focused property services. Since its launch, the department has focused on:

  • Being accessible and providing clear, practical advice throughout the property transaction process
  • Ensuring efficient and timely completion of conveyancing matters
  • Building long-term relationships with clients, estate agents, and mortgage advisors
  • Delivering a transparent and client-focused service

Under William’s leadership, Lacey Solicitors has become a trusted name for residential and commercial conveyancing in Northern Ireland.


Why Choose Lacey Solicitors?


When it comes to property law, clients want solicitors they can trust. William Wilson, Head of our Property Department, explains the vision behind our approach:

“Starting a property department from scratch in Northern Ireland is a significant challenge, primarily due to stringent lender requirements and the existing frameworks of many property firms. A lot of firms are set in their ways, relying on traditional practices that can hinder innovation.

Rather than joining an established firm solely for its reputation, I saw an opportunity to develop a client-centred approach that emphasises communication, efficiency, and cost-effectiveness.

Lacey Solicitors already boasts a proven track record in client care, evidenced by their Lexcel accreditation. This recognition demonstrates their commitment to quality service, which aligns perfectly with my vision for the new property department. Additionally, their significant investment in legal technology positions us to streamline processes and enhance client interactions effectively.

By starting the property department here, we can leverage Lacey’s existing strengths while implementing a fresh perspective focused on the client experience. I believe this approach not only differentiates us from traditional property firms but also meets the evolving demands of clients in today’s market.”


ESTAS Award Recognition – A Testament to Client Care

The ESTAS Awards have been recognising service excellence in the property sector for over 21 years. Unlike other awards, ESTAS are based solely on verified client feedback, making them a true reflection of service quality.

Being awarded Silver in the 2025 NI Conveyancer Awards highlights Lacey Solicitors’ commitment to:

  • Delivering service from the heart
  • Building trust and long-term relationships with clients
  • Providing a smooth, transparent, and stress-free conveyancing experience

This recognition shows clients and partners that Lacey Solicitors is a firm that not only talks about client service but consistently demonstrates it in practice.


Our Modern Approach to Conveyancing


At Lacey Solicitors, we combine decades of legal expertise with innovative technology to make property transactions faster, clearer, and more efficient. Our client-focused approach ensures:

  • Real-time updates on the progress of your transaction in a way that suits you
  • Reduced delays through streamlined document management and AI
  • Clear cost structures from the outset with no hidden fees
  • A dedicated team providing personalised guidance every step of the way

Whether you’re a first-time buyer, a property investor, or a commercial client, our team ensures that your property transaction is handled with precision, transparency, and care.


What Sets Our Property Department Apart


  • Lexcel-accredited firm recognised for excellence in client care
  • Award-winning team – Silver winners at the NI Conveyancer Awards 2025
  • Finalists at the 2025 Irish Law Awards – Property Law Firm of the Year
  • Innovative legal technology for efficient property transactions
  • Transparent pricing and client-focused service
  • Extensive knowledge of the Northern Ireland property market

By combining experience, technology, and a fresh perspective, Lacey Solicitors delivers conveyancing services that exceed expectations.


Contact Our Award-Winning Property Team


If you’re looking for trusted property solicitors in Northern Ireland or conveyancing solicitors in Belfast, Lacey Solicitors is here to help. Speak to William Wilson and our expert team today.

Roundabout Accidents in Northern Ireland. Who is at Fault?


Roundabouts keep traffic moving but they are also a common scene for collisions. Working out who is at fault in a roundabout accident can be complicated. Fault usually turns on who had right of way, who signalled correctly and whether any driver changed lanes or entered unsafely.

At Lacey Solicitors, we help innocent drivers, passengers, insurers, cyclists and pedestrians across Ireland and Northern Ireland resolve roundabout accident claims and assist in determining liabilty.


How Roundabouts Work


The Golden rule is always: traffic already on the roundabout has priority. Drivers entering must give way to vehicles approaching from the right. Both the Rules of the Road (Ireland) and Official Highway Code (Northern Ireland) require motorists to:

  • Give way to the right.
  • Use the correct lane for their intended exit.
  • Signal left when leaving.
  • Avoid sudden lane changes or cutting across traffic.

Common Causes of Roundabout Accidents in NI


  • Failing to yield to circulating traffic.
  • Entering or exiting from the wrong lane.
  • Changing lanes suddenly.
  • Not indicating correctly.
  • Tailgating or harsh braking.
  • Speeding or wet-weather skids.
  • Driver distraction.

Typical Fault Scenarios


1. Entering without giving way:
A driver who joins and collides with a vehicle already on the roundabout is normally at fault.

2. Lane discipline errors:
Drivers who cut across lanes or exit from the wrong lane may be fully or at least partially liable if an accident occurs.

3. Failure to signal:
Not indicating if it contributes to a collision can result in a driver being held to a degree liable for the accident.

4. Rear-end impacts:
Usually the rear driver will be found at fault.

5. Collisions with cyclists or motorcyclists:
These vulnerable road users should be afforded strong legal protection due to their increased risk of serious injury.  It is vital that you take care and look for cyclists and motorcyclists.


Proving Fault in Roundabout Accidents


Detailed documentation can help establish fault, clarify the circumstances of the accident, and protect your legal rights. Useful evidence includes:

  • Dashcam or CCTV footage.
  • Witness statements.
  • Garda or PSNI reports.
  • Photographs of vehicle positions and damage.
  • Time-stamped messages or insurer correspondence.

Shared Responsibility


Whether it is Sandyknowes Roundabout Glengormley or Caw Roundabout in Derry, an inescapable truth is that in many roundabout accidents, fault is often shared between the drivers.

Liability is often be apportioned where both parties contributed to the collision, perhaps through poor observation, incorrect lane use, or failure to signal properly. This legal principle, known as contributory negligence, can reduce the amount of compensation awarded to reflect each driver’s degree of responsibility.

For example, where both drivers contributed equally to the accident, your compensation might be reduced by 50%.

Useful evidence like the evidence outlined above is critical to assisting your car accident solicitor in proving the other driver is at fault.


What to Do After a Roundabout Accident


  1. Ensure everyone is safe.
  2. Exchange driver and insurance details.
  3. Take photos of the scene if it is safe to do so.
  4. Report serious incidents to Gardaí or PSNI.
  5. Seek legal advice before speaking to insurers.

How Lacey Solicitors Can Help


With offices in Dublin and Belfast, Lacey Solicitors represent clients in all types of road traffic accident claims, including complex liability disputes arising from roundabout collisions.

Our experienced team can:

  • Investigate fault and liability using expert accident reconstruction and evidence analysis.

  • Engage directly with insurers and third parties to progress your claim efficiently.

  • Pursue full compensation for your injuries, vehicle damage, loss of earnings, and related expenses.

We provide clear, practical legal advice and ensure that every client receives a personal, professional, and transparent service from start to finish.

Lacey Solicitors Belfast & Dublin : The Implications of Farley v Equiniti for Data Protection and Data Breach Claims


At Lacey Solicitors, with offices in Belfast and Dublin, our data protection solicitors represent clients affected by high-profile data breaches across the entire island of Ireland. The Court of Appeal ruling in Farley and Others v Paymaster (1836) Limited (trading as Equiniti) [2025] EWCA Civ 1117 has solidified the approach to compensation for data protection breaches in the UK – a development highly relevant for both clients and organisations seeking guidance from expert data protection solicitors on the issue of a data breach.

The focus of the Court of Appeal was the confirmation that there is no minimum threshold of harm for claims under Article 82 of the UK GDPR or section 168 of the Data Protection Act 2018 (DPA 2018).

A claimant can therefore seek compensation for a minor claim of distress or fear of misuse of personal data.


What Happened in Farley


The case arose after Equiniti, administrator of the Sussex Police pension scheme, accidentally sent over 750 annual benefit statements to outdated addresses. These statements contained sensitive information including names, dates of birth, National Insurance numbers, salaries, and pension entitlements.

Following the breach, a claim form was issued on behalf of 474 current and former officers, seeking damages for breach of statutory duty under the UK GDPR and the DPA and/or misuse of private informationarising from the [respondent’s] failure to keep the claimants’ personal data and private information secure by posting the same to incorrect postal addresses.


The High Court Decision


At first instance, Mr Justice Nicklin struck out most claims, leaving only fourteen claimants whose letters had been physically opened. Only two could show that someone outside their family or workplace had actually read the documents.

The High Court applied a “de minimis” principle, dismissing claims that weren’t considered sufficiently serious. The court concluded that the mere risk of disclosure—without evidence that the information had been seen—was not enough to support compensation.


The Court of Appeal


The Court of Appeal overturned much of the High Court’s decision, clarifying several important principles relevant for individuals consulting data protection solicitors:

  • Proof of disclosure is not required: Data does not need to have been accessed by a third party for processing or an infringement to occur. The term “processing” covers all steps, including collating, printing, and sending letters.
  • Distress is not essential: Non-material damage can be claimed even without proving distress, though compensation does not cover every emotional reaction to a breach.
  • No threshold of seriousness: Claims under the GDPR do not require a minimum level of harm.
  • Fear of misuse must be well-founded: Where claims are based on fear that personal data could be misused by third parties, the fear must be objectively reasonable, based on what the claimant knew or should have known at the time.
  • Future harm is compensable: A claimant may have a well-founded fear of future misuse, even if no actual harm occurs.

These findings emphasise that data protection claims focus on the unlawful processing of personal data, rather than solely on whether actual harm or disclosure occurred.


The Irish Supreme Court in Dillon v Irish Life


In a previous article, our office highlighted the Irish Supreme Court Decision in Dillon v Irish Life Assurance.  This Decision was referenced by the English Court of Appeal who acknowledge that victims of data breaches who seek compensation “solely for mental distress, upset and anxiety … cannot expect anything other than very, very modest awards”

But the English Court of Appeal went on to say that some of the claims in the case encompass psychiatric injury and the modest scale of the likely recovery cannot of itself be sufficient to justify dismissal of the claim.

The Judge referenced Lewison LJ  Sullivan v Bristol Film Studios [2012] EWCA Civ 570, [2012] EMLR 27, [29]:The mere fact that a claim is small should not automatically result in the court refusing to hear it at all. If I am entitled to recover a debt of £50 …. it would be an affront to justice if my claim were simply struck out.”


Data Protection Breach or Misuse of Private Information


At Lacey Solicitors, one of the key distinctions that we often have to make clear to our client’s is the difference between Data Breach Claims and Misuse of Private Information Claims.  Both are, in our opinion erroneously, used interchangeably.

What Is a Misuse of Private Information Claim?


A misuse of private information claim is a common law tort that has evolved in light of Article 8 of the Human Rights Act 1998, which protects the right to respect for private and family life.  It arises when private information is disclosed without consent, even if data protection laws are not breached. Key elements include:

  • Expectation of Privacy: The information must be private, and the individual must reasonably expect it to remain confidential.
  • Unauthorised Disclosure: The information must be shared without consent.
  • Harm or Distress: The disclosure must cause harm or distress.


How It Differs from a Data Protection Breach


  • Legal Basis: Data protection breaches are statutory claims under UK GDPR and DPA 2018; misuse of private information claims are common law.
  • Scope: Data protection claims cover lawful handling of personal data, including collection, storage, and sharing. Misuse of private information focuses on unauthorised disclosure.

What You Should Know About Data Protection Breaches in Northern Ireland & Ireland


For individuals, the decision is significant: even minor breaches can entitle them to compensation for distress or fear of misuse.

For organisations, the implications are clear: even small errors in handling personal data carry liability. Businesses should consult data protection solicitors to ensure robust data governance, clear processes, and effective breach communication.

At Lacey Solicitors, we advise clients on risk management, compliance, and breach response, and represent individuals affected by high-profile data breaches across the entire Island of Ireland.


Conclusion


Farley v Equiniti strengthens the rights of individuals affected by data breaches. By removing the de minimis threshold, the Court confirmed that fear of misuse and emotional distress are valid grounds for compensation, even without actual disclosure.

For organisations, the judgment highlights the importance of compliance and proactive breach management. For individuals, it demonstrates that personal data rights carry real legal protections.

At Lacey Solicitors, as experienced data protection solicitors, we continue to represent clients in high-profile data breach claims, helping them secure compensation and protections under the law. Cases such as Farley, Lloyd v Google [2021] UKSC 50, Prismall v Google UK Ltd [2024] EWCA Civ 1516, and Rolfe v Veale Wasbrough Vizards Ltd [2021] EWHC 2809 (QB) form a strong foundation for our work in this area.

Consent in Medical Negligence in Northern Ireland. Lacey Solicitors Belfast Summarise the Key Case Law.


Consent is a central issue in medical negligence law. Patients are entitled to make informed decisions about medical treatment, and doctors have a legal duty to disclose risks and alternatives that are material to the patient’s decision. Failure to obtain proper consent may constitute negligence, even if the procedure itself is performed competently.

This article analyses the development of consent law through key UK and international cases.


Bolam v Friern Hospital Management Committee [1957]


Bolam established the foundational test for medical negligence: a doctor is not negligent if they act in accordance with a practice accepted as proper by a responsible body of medical opinion. However, this principle is limited: professional opinion must be capable of withstanding logical analysis; otherwise, it cannot excuse negligence.

Bolam initially governed both the standard of care in treatment and the scope of disclosure to patients.  For a more detailed discussion of the application of the Bolam and Bolitho tests in Northern Ireland and the Republic of Ireland, see our previous article Medical Negligence Claims: The Difference in Northern Ireland and the Republic of Ireland.


Canterbury v Spence [1972]


Although an American case, Canterbury v Spence is frequently cited in discussions of consent. The claimant was not informed of a 1% risk of paralysis from spinal surgery.

The court emphasised a “prudent patient” standard, focusing on what a reasonable patient would wish to know rather than what a doctor deemed necessary. This case introduced the principle that consent should prioritise patient autonomy.

The ruling represented a major shift from the traditional medical standard (known as the Bolam test in the UK) where a doctor’s duty of care was judged by other doctors. Instead, the court prioritized patient autonomy and the patient’s right to self-determination. 


Sidaway v Bethlem Royal Hospital [1985]


In Sidaway, the House of Lords confirmed a doctor-centred approach to consent under UK law: disclosure of risks is largely a matter of professional judgment. If a responsible body of medical opinion would not have warned the patient of a particular risk, failure to disclose would not constitute negligence. Sidaway reinforced the dominance of Bolam in disclosure cases until later reforms.


Chester v Afshar [2004] – Causation and the Right to Choose


Chester marked a critical development in consent law, particularly regarding causation. The claimant underwent back surgery without being warned of a 1% risk of paralysis.

Ordinarily, negligence requires establishing a “but for” causal link: the injury would not have occurred but for the breach. The House of Lords recognised that strict application of the “but for” test could undermine the patient’s right to make an informed choice. Key points:

  • What matters is whether the patient was denied the opportunity to make an informed choice at the relevant time.
  • A claimant does not need to show they would never have had the procedure, only that they would have deferred it or sought further advice.

Lord Hope stated:

“The function of the law is to protect the patient’s right to choose. If it is to fulfil that function, it must ensure that the duty to inform is respected by the doctor.”

Chester established that failure to warn can constitute negligence in itself, modifying the traditional causation requirement in this narrow context.


Montgomery v Lanarkshire Health Board [2015] – Modern Test for Consent


Montgomery is the leading authority on consent in England and Wales. The claimant, a small woman with diabetes, was not informed of a 9–10% risk of shoulder dystocia during vaginal delivery. The doctor did not disclose this risk, believing the patient would otherwise opt for a C-section, which he considered not in her best interests.

The Supreme Court clarified the law:

  • An adult of sound mind is entitled to decide which, if any, treatment to undergo. Consent must be obtained before any intervention affecting bodily integrity.
  • Doctors have a duty to take reasonable care to ensure the patient is aware of any material risks and reasonable alternatives.
  • The materiality test is whether a reasonable person in the patient’s position would attach significance to the risk, or if the doctor knows or should reasonably know that the particular patient would attach significance.

Montgomery firmly shifted UK law to a patient-centred standard, prioritising autonomy over professional discretion.


Deuce v Worcester Acute Hospitals NHS Trust [2018] – Limits of Chester


In Deuce, the claimant underwent a total abdominal hysterectomy and subsequently developed neuropathic post-surgical pain. She claimed the Trust failed to warn her of the risk of chronic post-surgical pain, material under Montgomery.

The trial judge found:

  • No negligence in disclosure.
  • Causation not established; the claimant would have undergone the surgery regardless.

On appeal, the Court of Appeal confirmed:

  • The Montgomery test had been correctly applied.
  • The modified causation rule in Chester does not remove the need to show a “but for” link — specifically, that the surgery would not have occurred at the relevant time.
  • Following Correa v University Hospital of North Staffordshire NHS Trust, if relying on Chester’s exceptional principle, it must be pleaded and proved that the claimant would have deferred surgery had the risk been disclosed.

Deuce illustrates the limits of Chester: it does not create a general relaxation of causation, but applies only where the claimant can demonstrate that informed choice would have affected the timing of the procedure.


Bilal and Malik v St. George’s University Hospitals NHS Foundation Trust – Determining Alternative Treatments


Bilal and Malik considered the correct approach to offering alternative forms of treatment: should this be assessed under the Bolam test (a question for the medical professional) or under Montgomery (a question for the patient)?

  • Under Bolam, a doctor would not be negligent if a reasonable body of medical opinion agreed that it was acceptable to withhold or recommend certain treatments.
  • Under Montgomery, materiality is judged from the patient’s perspective, focusing on whether a reasonable patient would attach significance to the risk or treatment choice.

Judge Davies clarified that these principles operate in tandem:

  1. It is for the doctor to assess what reasonable alternatives exist for treatment — i.e., the medical assessment of options remains guided by professional judgment under Bolam.
  2. It is for the court to determine the materiality of the risks associated with each proposed treatment. The test is whether a reasonable person in the patient’s position would attach significance to the risk.

This distinction preserves the doctor’s expertise in evaluating treatment options while ensuring that disclosure of material risks and alternatives is judged according to patient-centred standards under Montgomery.


Summary and Conclusion


  1. Bolam remains good law for ordinary clinical negligence cases. The standard of care is still assessed by reference to a responsible body of medical opinion capable of withstanding logical analysis.
  2. Material risks and reasonable alternatives must be judged from the perspective of the prudent patient, not by reference to professional practice. This principle was established in Montgomery: disclosure is patient-centred, focusing on what a reasonable person in the patient’s position would consider significant.
  3. Causation in consent cases generally follows the ordinary “but for” rules. However, the test is modified in limited circumstances where the claimant can demonstrate that, had they been properly informed, they would have taken time to consider their options before consenting. This was seen in Chester v Afshar and reaffirmed in Deuce.
  4. Alternative treatments — whether they are reasonable and should be brought to the patient’s attention — remain a professional practice matter, assessed under the Bolam standard. This approach was clarified in Bilal and Malik. The doctor determines which treatment options are reasonable; the court assesses which risks are material for disclosure to the patient.

In essence, the law draws a careful distinction: medical judgment governs what treatments are reasonable, but patient autonomy governs what risks and alternatives must be disclosed. Practitioners must consider both elements when advising clients or evaluating potential claims.


Contact Lacey Solicitors Belfast & Dublin – Medical Negligence Solicitors


At Lacey Solicitors, our approach to medical negligence claims is straightforward and client-focused. We begin by listening carefully to your story and explaining your legal options in plain English. From there, we gather the necessary medical evidence and reports to support your case, and we fight diligently for fair compensation and justice. If you or a loved one has suffered due to medical negligence in Northern Ireland or the Republic of Ireland, we are here to help.

Trust our experience and let us help you move forward. Use our Online Portal and a solicitor will contact you within 24 hours for a few no-obligation chat.